


INCLUSIVE GROWTH IS REFLECTED IN THE POLICIES AND REGULATIONS THAT GOVERNMENT OF INDIA AND INSTITUTIONS LIKE RBI, IRDA , PFRDA , ETC., HAVE BEEN DEVELOPING OVER THE PAST DECADE. THESE POLICIES HAVE ENABLED BANKING SECTOR TO TAKE A LEAD ROLE IN PROMOTING FINANCIAL INCLUSION

While the growth that India has seen during the past decade has been impressive, poverty and financial exclusion continue to dominate the socio-economic and political discourse. Even though the Indian economy has recorded impressive growth rates until recently, its impact has sadly not fully percolated to the lowest deciles, because large sections of our society continue to be excluded from the financial system. In developing economies like ours, the banks, as mobilisers of savings and allocators of credit for production and investment, have a very critical role. Hence the financial sector has a tremendous role to play the role of an agent of change and ensure redistribution of wealth in the society.
| Position of Households availing banking services | ||||||
| As per Census 2001 | As per Census 2011 | |||||
| Households | Total Number of Households |
Number of households availing banking services |
Percent | Number of households availing banking services |
Total Number of Households |
Percent |
| Rural | 138,271,559 | 41,639, 949 | 30.1 | 167,826,730 | 91,369,805 | 54.4 |
| Urban | 53,692,376 | 26,590,693 | 49.5 | 78,865,937 | 53,444,983 | 67.8 |
| Total | 191,963,935 | 68,230,642 | 35.5 | 246,692,667 | 144,814,788 | 58.7 |
Extent of Financial Exclusion in India
Financial inclusion attempts to deliver financial services at affordable costs to the common man so that large sections of society can be served. During the last few years the Government of India has taken a large number of initiatives in order to promote financial inclusion. Financial inclusion and unemployment are also found to be correlated. Along with various poverty eradication and employment generation programmes, focus should also be on the financial inclusion policies as a means of ameliorating interwoven case of poverty and unemployment.

In the past, the Public Sector banks in India have demonstrated resilience in the face of the recent global financial crisis, nevertheless, these banks should adopt strong and urgent measures to reach the unbanked segment of society and unlock their savings and investment potentials. To accomplish this task, a majority of the Public Sector banks have already adopted the Core Banking Solutions (CBS). Appropriate technologies have to be in place for promoting financial inclusion. For the Government of India, inclusive growth has always been a priority. The agenda of inclusive growth is reflected in the kind of policies and regulations that the policymaking and regulating institutions, like- Government of India, RBI, IRDA, PFRDA (for micro-pensions), – have been developing over the past decade. The banking sector has taken a lead role in promoting financial inclusion.

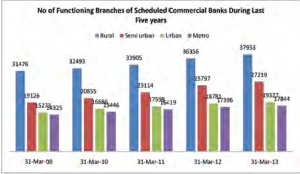
There has been in multi-fold increase in the number of back branches, especially in rural areas; the branch network was around 8,000 in 1969 and now it is more than 89,000, spread across the length and breadth of the country. “The costs of providing financial services to all citizens can be brought down by enabling financial institutions in the country with innovative solutions from ICT,” says Anurag Jain, Joint Secretary, Department of Financial Services, Ministry of Finance.

The KYC norms for bank accounts with smaller sums of money have already been relaxed. In rural areas we have a system where the new account holders can be introduced by local citizens. Aadhaar can also be very useful for financial inclusion, as it provides all the citizens of the country a rather foolproof way of proving their identity in an easy and seamless manner. Also now Public Sector banks providing the poor and marginalized sections of the population a choice of a ‘no frills account’ where the minimum balance is nil or very small but having restrictions on number of withdrawals, etc., to facilitate easy access to bank accounts.

 Dr K C Chakrabarty Deputy Governor, Reserve Bank of India“We have defined Financial Inclusion as the “process of ensuring access to appropriate financial products and services needed by all sections of the society in general and vulnerable groups such as weaker sections and low income groups in particular, at an affordable cost in a fair and transparent manner by regulated, mainstream institutional players”. We consider Financial Inclusion and Financial Literacy as twin pillars where Financial Inclusion acts on the supply side i.e. for creating access and financial literacy acts from the demand side i.e. creating a demand for the financial products and services” |
Initiatives in Rural Areas
The villages in India are witnessing a flurry of activity, thanks to the financial inclusion initiatives of banks. Most of the banks are now busy appointing business correspondents (BC) or opening up ultra small branches in villages under the financial inclusion plan. The banks have also launched a pilot project on smart card based business transactions through Business Correspondents (BC) model. As financial illiteracy and lack of basic education are the prohibiting factors leading to non-access of financial services, the Public Sector banks are taking many initiatives to educate the local population in modern banking system. There are more interactions between the bank officials and the rural population, so that the people in rural areas develop confidence in modern banking.
 Many of the Public Sector Banks have also developed efficient initiatives to resolve grievances regarding the services being rendered by the Business Correspondents. A Grievance Redressal Officer has been appointed in each Zone to ensure that the grievances received from the clients in rural areas are promptly and satisfactorily dealt with. In case, the compliant remains unresolved for up to 60 days of filing, the client has the option of approaching the Office of the Banking Ombudsman concerned for redressal of his grievance. The list of grievance redressal officers is usually given at the website of the Public Sector Bank.